If you’re living in Massachusetts and own a car, you’ve likely asked yourself, “How much is auto insurance in Massachusetts?” Well, you’re not alone. Navigating the world of auto insurance can often feel like solving a Rubik’s cube blindfolded. But fear not, in this guide, we’re going to dismantle the complexities and make everything crystal clear for you.
Let’s face it: insurance isn’t the most exciting topic on Earth, but it’s crucial. Understanding what influences your rates, what coverage you need, and how you can get the best deal is essential for every driver. So buckle up; we’re about to take you on a journey through the ins and outs of Massachusetts auto insurance, Backlinko style.
Understanding Auto Insurance Requirements in Massachusetts
Did you know that driving without the right auto insurance in Massachusetts could cost you big time? It’s not just a legal issue—it’s a financial risk you can’t afford to take.
Massachusetts has specific auto insurance requirements that every driver must meet. These aren’t just suggestions—they’re mandated by state law. If you’re cruising around the Bay State, here’s what you need to know.
Mandatory Auto Insurance Coverage in Massachusetts
Every driver in Massachusetts is required to purchase auto insurance. But it’s not just any insurance; you need to meet specific minimum liability limits. Here’s the deal: the state requires liability coverage that includes Bodily Injury to Others, Personal Injury Protection (PIP), Bodily Injury Caused by an Uninsured Auto, and Damage to Someone Else’s Property.
Let’s break it down:
- Bodily Injury to Others: Minimum of $20,000 per person and $40,000 per accident.
- Personal Injury Protection (PIP): Up to $8,000 per person.
- Bodily Injury Caused by an Uninsured Auto: Minimum of $20,000 per person and $40,000 per accident.
- Property Damage: At least $5,000 per accident.
Failing to meet these minimums means you’re driving illegally. Even worse, if you’re caught, you could face fines, license suspension, or even jail time.
Consequences of Not Having Required Insurance Coverage
Picture this: you’re driving without insurance and get into an accident. Suddenly, you’re looking at personal liability for damages. Not fun, right? The financial burden can be overwhelming without insurance to back you up.
Pro Tip: Always carry proof of insurance in your vehicle. It’s your best defense during a traffic stop or after an accident.
But here’s the kicker—if you’re caught without insurance in Massachusetts, penalties can hit hard. Besides fines and fees, you could face a potential license suspension of up to 60 days. And repeat offenses lead to even harsher punishment.
Factors Influencing Auto Insurance Costs in Massachusetts
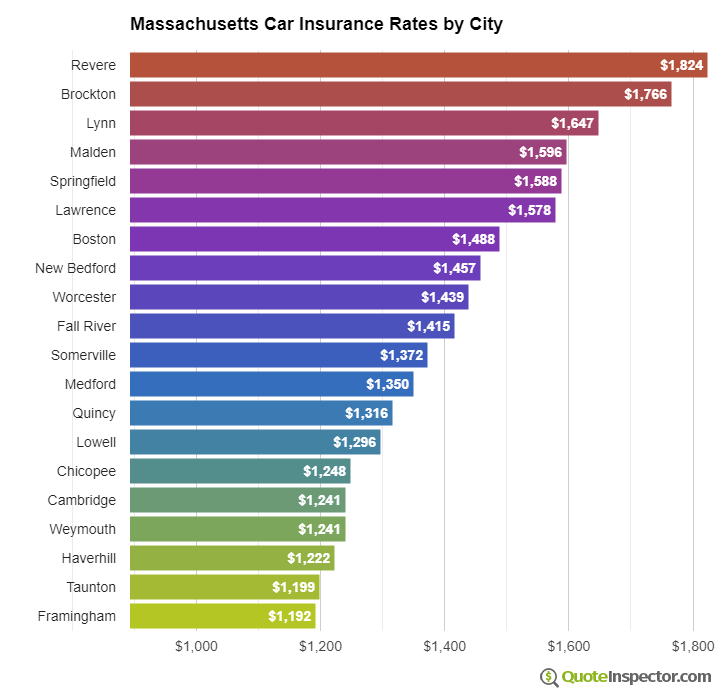
Did you know that Massachusetts has some of the highest auto insurance rates in the country? It’s true! But what exactly drives these costs up—or down?
The price you pay isn’t just a random number. It’s the result of several key factors that insurers consider to determine your risk level. From your age to your driving record, and even where you park your car at night, all these details play a role in how much you end up paying.
Age, Driving Record, and Vehicle Type
First things first: your age matters. If you’re under 25, brace yourself for higher premiums. Insurers see younger drivers as riskier because they are statistically more likely to get into accidents.
Your driving record is another critical factor. Have a clean slate? That’s great news—expect lower rates. But if you’ve had a few too many fender benders or traffic violations, your premiums will shoot up faster than you can say “speeding ticket.”
What about your car? The type of vehicle you drive significantly impacts your insurance costs. Sporty, high-performance cars tend to cost more to insure than sedans or family SUVs. Why? They’re more likely to be stolen and cost more to repair.
Location, Location, Location
Where you live in Massachusetts can make a big difference in your insurance bill. Urban areas like Boston will hit your wallet harder than rural spots. Why? More cars, more traffic, more accidents. It’s a simple equation.
But here’s the deal: even within the same city, different neighborhoods can have varying rates based on crime statistics and accident frequency. So, your ZIP code could be working for—or against—you when it comes to premiums.
Pro Tip: Regularly review your insurance coverage to ensure you’re getting the best deal. If your circumstances change—like moving to a safer neighborhood—update your policy to potentially lower costs.
Comparing Auto Insurance Providers in Massachusetts
Ever wondered which auto insurance provider truly offers the best bang for your buck in Massachusetts? You’re not alone. With so many options on the market, it’s easy to feel overwhelmed. BUT, here’s the deal: not all insurers are created equal.
To help you make an informed decision, we’re going to dive into a side-by-side comparison of the major players in Massachusetts. We’ll look at coverage options, customer ratings, and what makes each company unique. Let’s break it down!
Major Auto Insurance Providers and Their Offerings
Here’s a quick look at how top auto insurance companies stack up in Massachusetts. Each has unique features that might just align perfectly with what you’re looking for.
| Provider | Coverage Options | Customer Ratings |
|---|---|---|
| State Farm | Liability, Collision, Comprehensive | 4.5/5 |
| GEICO | Liability, Uninsured Motorist, Medical Payments | 4.3/5 |
| Progressive | Liability, Collision, Roadside Assistance | 4.2/5 |
| Liberty Mutual | Liability, Comprehensive, Rental Reimbursement | 4.4/5 |
Unique Selling Points of Top-Rated Insurance Companies
Each of these companies has something special to offer. For instance, State Farm stands out with its vast network of agents and personalized service. GEICO is known for its competitive rates and easy-to-use online tools. Progressive offers the popular “Name Your Price” tool, which helps you find coverage that fits your budget.
Liberty Mutual provides extensive discounts, especially for safe drivers. These perks can make a big difference when you’re trying to save money on your policy.
Evaluating Customer Service and Claim Processes
It’s crucial to look beyond price and delve into how each company handles customer service and claims. Step #1 is to check online reviews and ratings. Customers frequently highlight how quickly claims are processed and how easily they can reach customer support.
Step #2 is to contact the companies directly. Ask about their claims process and average turnaround times. This direct communication gives you a feel for their customer service quality.
Pro Tip: Always read the fine print of your policy to avoid any surprises during a claim.
Discounts and Savings Opportunities for Massachusetts Drivers
Are you overpaying for auto insurance in Massachusetts? You might be leaving money on the table by missing out on discounts you’re eligible for.
Insurance companies in Massachusetts offer a wide range of discounts that could save you a bundle. Here is the deal: you could slash your premium by simply taking advantage of these discounts and adjusting your driving habits.
Common Auto Insurance Discounts Available
Most insurers in Massachusetts offer a variety of discounts. These can make a significant dent in your premium.
- Multi-policy discount: Bundle your auto insurance with home or renters insurance.
- Safe driver discount: Keep a clean driving record for 3 years or more.
- Good student discount: If you’re a student with a B average or better.
- Anti-theft discount: Install an approved anti-theft device in your car.
- Low mileage discount: Drive less than the insurer’s defined low mileage threshold.
Qualifying for Premium Reductions
It’s easier than you might think to qualify for these discounts. BUT, you need to know the steps.
- Check with your insurer to see which discounts you already qualify for.
- Consider bundling your policies to access multi-policy discounts.
- Maintain a clean driving record to maximize your safe driver savings.
- Participate in a defensive driving course to gain additional discounts.
- Proactively ask your insurance agent about any new discounts.
Safe Driving Habits That Lead to Savings
Safe driving can pay off big time in Massachusetts. Here’s how:
By avoiding traffic violations, you can maintain or achieve a safe driver discount. If you stay accident-free, your premiums can be significantly lower. Insurers reward drivers who demonstrate responsibility.
Pro Tip: Consider using a telematics device offered by your insurer to monitor and improve your driving habits. This could lead to substantial savings!
Ultimately, by being proactive and informed, you can significantly reduce your auto insurance costs in Massachusetts. Start by checking if you qualify for any of these discounts right now!
The Role of Massachusetts’ No-Fault Insurance System
Did you know that Massachusetts operates under a no-fault insurance system? This means that after an accident, your insurance pays for your own injuries, regardless of who caused the crash.
Here’s how it works: when you’re involved in an accident, you don’t need to prove who was at fault to get your medical bills covered. This system aims to reduce costly and lengthy legal battles over accident fault. However, it doesn’t cover everything, and there are limits to what you can claim.
Benefits and Limitations of No-Fault Insurance
The no-fault system in Massachusetts offers several benefits to drivers. First, it ensures quicker payouts, so you can focus on recovery rather than legal proceedings. Plus, it reduces the likelihood of lawsuits arising from minor accidents. But there’s a catch: you can’t sue the other party for pain and suffering unless your medical expenses exceed a certain threshold.
Impact on Insurance Claims and Premiums
Under this system, your ability to claim certain damages is limited, which can sometimes lower the overall costs for insurers. This can lead to more competitive premiums for drivers. However, if you find yourself frequently at fault, your premiums could skyrocket due to increased personal injury claims.
Pro Tip: Regularly review your insurance policy to understand how your premium is affected by the no-fault system.
In summary, while the no-fault system simplifies the process of getting compensation, it also means you need to be aware of the limits and how it impacts your total insurance costs.
Tips for Reducing Auto Insurance Costs in Massachusetts
Did you know that the average cost of car insurance in Massachusetts is $1,223 per year? That’s right! But you’re not stuck with that price. There are ways to lower your premiums and save some serious cash.
Here’s the deal: a little effort can lead to big savings. From comparing quotes to maintaining a stellar driving record, let’s dive into some savvy strategies.
Step-by-Step Guide for Comparing Insurance Quotes
If you want to snag the best deal on auto insurance, you need to shop around. Start by gathering quotes from at least three different insurers. But don’t just look at the price. Pay attention to the coverage details, deductibles, and any special terms.
- Use online comparison tools to streamline the process.
- Contact insurance agents directly to clarify details.
- Re-evaluate your quotes annually or with any major life change.
Pro Tip: Insurers often offer customized deals if you ask the right questions.
Strategies for Maintaining a Clean Driving Record
A spotless driving record can be your golden ticket to lower insurance premiums. How? Insurers love low-risk drivers!
- Avoid traffic violations and speeding tickets at all costs.
- Consider defensive driving courses for potential discounts.
- Be aware of Massachusetts’ “surchargeable incidents” that affect your record.
Pro Tip: Some insurers offer vanishing deductible programs for incident-free driving years.
Advantages of Bundling Auto Insurance with Other Coverage
Bundling isn’t just for cable TV. When you combine your auto insurance with home or renters insurance, you could see significant savings. Why? Insurers reward loyalty, and bundling demonstrates commitment.
- Check how much you save by combining different policies.
- Ensure that the bundled coverage meets all your needs without gaps.
- Review bundled policy terms periodically to ensure they’re still beneficial.
Pro Tip: Bundling discounts can be as high as 25%, so it’s worth exploring!
Last Word
And there you have it—your go-to guide for understanding how much auto insurance is in Massachusetts. With this knowledge, you’re all set to make informed decisions and potentially save a heap of cash. Remember, keeping an eye on your driving habits and exploring discounts can significantly impact your premiums. Drive safe, and enjoy the peace of mind that comes with being well-insured.
Common Queries
What are the minimum auto insurance requirements in Massachusetts?
Massachusetts requires drivers to carry a minimum of $20,000 per person and $40,000 per accident in bodily injury liability, along with $5,000 in property damage liability.
How does age affect auto insurance rates in Massachusetts?
Younger drivers often face higher premiums due to their lack of driving experience and higher risk factors.
Can my driving record influence my insurance costs?
Yes, a clean driving record can lower your premiums, while traffic violations or accidents can increase your rates.
Are there discounts available for auto insurance in Massachusetts?
Many providers offer discounts for safe driving, bundling policies, and even for being a good student. It’s worth asking your insurer for available discounts.
What is the no-fault insurance system in Massachusetts?
The no-fault system means each driver’s insurance covers their own injuries, regardless of who caused the accident, up to a certain limit.
