Welcome to the ultimate guide on securing the best insurance rates in North Carolina! Whether you’re new to the state or a long-time resident, understanding your insurance options can be a game-changer. From auto to health, and everything in between, we’ve got the scoop on how to navigate the insurance landscape in the Tar Heel State.
In this comprehensive breakdown, we’re diving deep into the types of insurance available, the factors influencing rates, and strategies to save money. Let’s explore how you can make informed decisions and get the best bang for your buck. Buckle up, because this journey is packed with valuable insights and tips you’ll want to bookmark!
Types of Insurance Available in NC
Did you know that nearly 12% of North Carolinians are uninsured? That’s a shocking figure, especially when you consider the variety of insurance options available in the state. If you’re looking for insurance in North Carolina, you’re in the right place.
From health to home, car to life insurance, NC has a wide array of options. But navigating through these can be daunting. Let’s break it down so you can easily find what suits your needs best.
Health Insurance Options
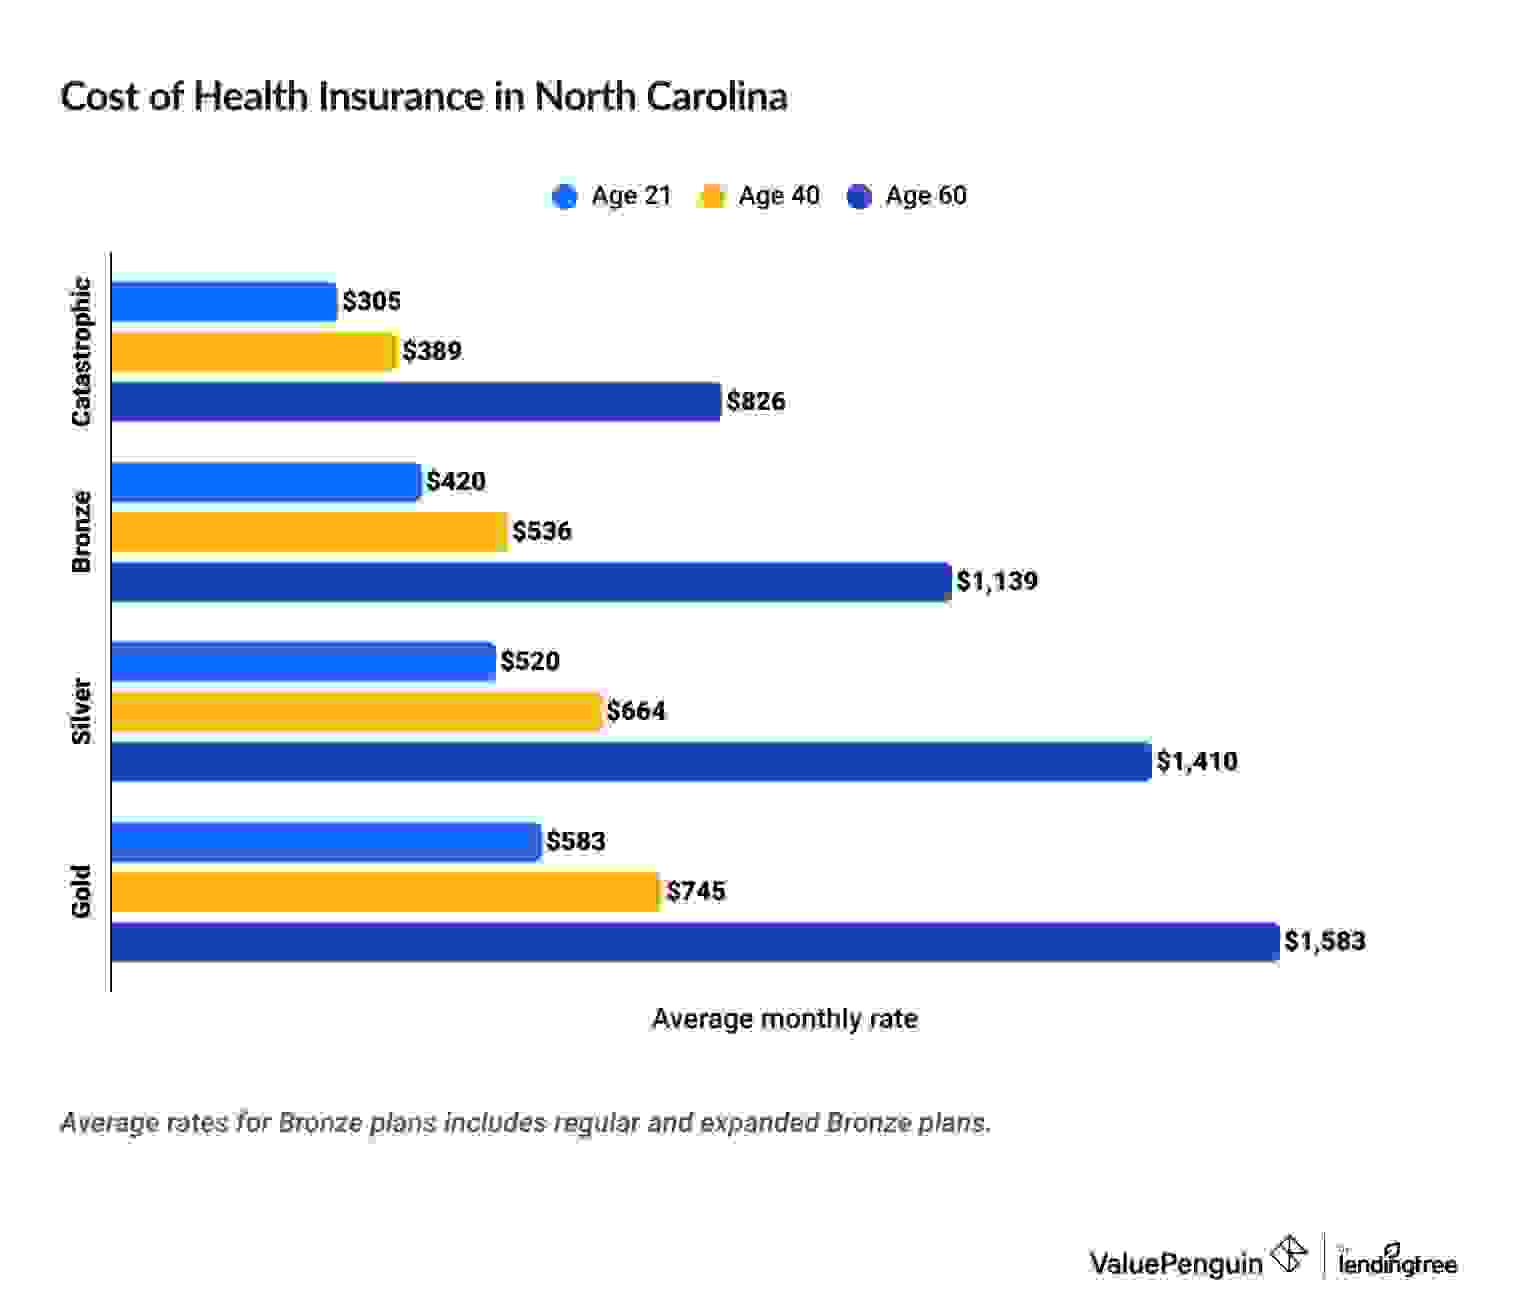
Health insurance is a must, but with so many plans, where do you start? In NC, you can choose from employer-sponsored plans, individual marketplace plans, and government programs like Medicaid. Each comes with its own set of coverage specifics, deductibles, and networks.
Car Insurance Essentials
Car insurance isn’t just a legal requirement; it’s your financial safety net on the road. North Carolina offers liability, comprehensive, and collision coverage. The minimum liability coverage required by law is 30/60/25, which might not be enough for everyone.
Homeowners Insurance Coverage
Your home is likely your biggest investment. Protect it with the right insurance. In NC, standard homeowner policies include dwelling, personal property, liability, and additional living expenses coverage. But, don’t forget flood insurance; it’s not always included.
Life Insurance Policies
Want to secure your family’s future? Life insurance in NC comes in two main types: term life and whole life. Term life is more affordable but lacks investment benefits. Whole life builds cash value over time, offering a dual benefit.
Insurance Type Comparison
Here’s a quick comparison guide to help you decide:
| Type | Coverage | Average Rate | Popular Providers |
|---|---|---|---|
| Health | Preventive, Emergency, Chronic | $450/month | Blue Cross NC, Aetna |
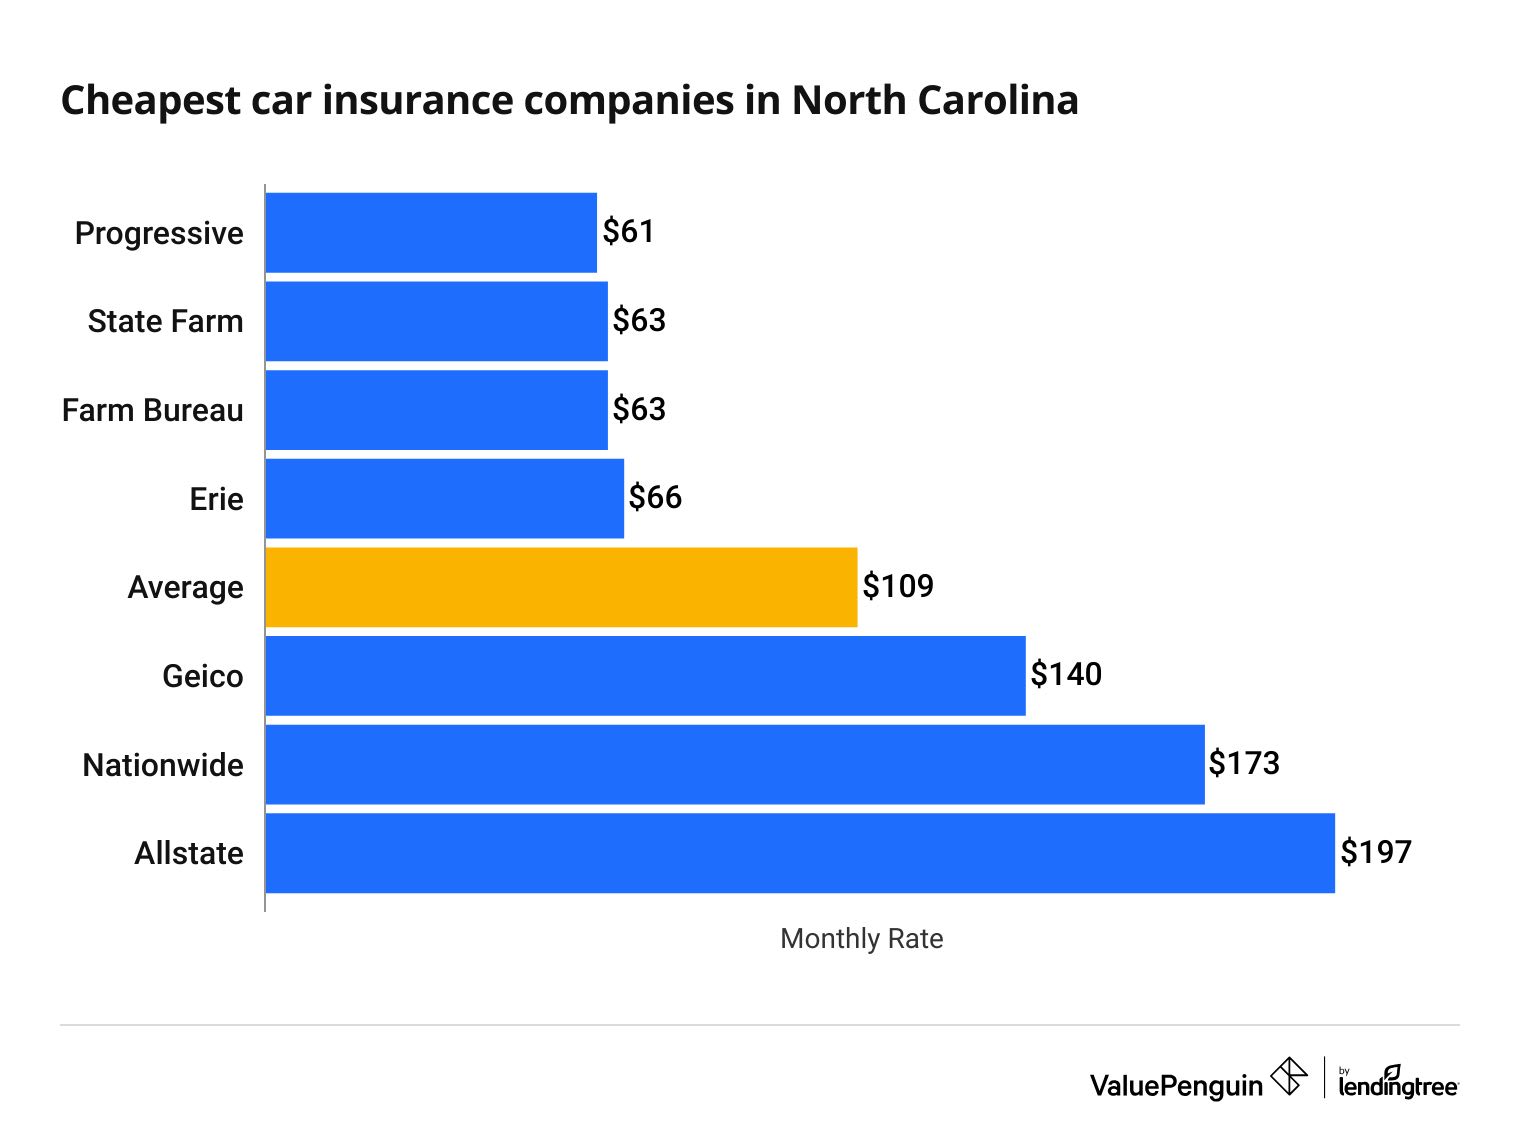
| Car | Liability, Comprehensive, Collision | $1,200/year | State Farm, Geico |
| Home | Dwelling, Personal Property, Liability | $1,000/year | Allstate, Nationwide |
| Life | Term, Whole | $800/year | MetLife, Prudential |
Pro Tip: Always compare at least three quotes before making a decision.
Factors Influencing Insurance Rates in NC
Ever wondered why two neighbors in North Carolina pay drastically different rates for the same insurance policy? You’re not alone. Insurance rates can feel like a mystery, but they don’t have to be.
Here is the deal: a combination of factors can skyrocket or slash your insurance premiums. Understanding these can help you make smarter choices and maybe even save some serious cash.
Location’s Impact on Insurance Rates
Your ZIP code is more than just some numbers on your mail—it’s a major player in your insurance rates. Why? Because certain areas are more prone to natural disasters, accidents, or thefts.
- Charlotte: Higher rates due to urban congestion.
- Raleigh: Moderate rates, less congestion.
- Outer Banks: Elevated rates, coastal risks.
The city you live in can significantly affect your rate. So, moving just a few miles could either lighten or weigh down your premium.
Credit Score and Its Role
Your credit score doesn’t just impact loans; it’s a huge factor in determining your insurance costs. Insurers see a low score as a higher risk, which can mean higher premiums for you.
Pro Tip: Regularly check your credit report to ensure it’s accurate. Even small errors can cost you big on insurance.
A solid credit score could be your ticket to lower payments, so it pays (literally) to keep it in check.
Driving Record: A Direct Influence
Your driving record is like your insurance report card. A clean slate can result in lower rates, but even a single infraction can spike your premiums.
Speeding tickets, DUIs, or accidents? They all have a direct impact on your costs. Insurance companies keep a close eye on your record because it helps them predict future behavior.
Insurance Claims History’s Effect on Premiums
The more claims you file, the more likely you are to pay higher premiums. Insurers interpret multiple claims as a sign of risk, and they adjust your rates accordingly.
However, strategic choices can mitigate this. For example, consider paying out of pocket for small damages to keep your claims history clean and your rates stable.
Remember: Insurance is a game of risk. Minimize yours, and you’ll maximize your savings.
Finding the Best Insurance Providers in NC
Did you know that choosing the wrong insurance provider could cost you hundreds or even thousands of dollars? It’s true! The right provider isn’t just about low prices—it’s about quality service and reliability.
Now, let’s dive into the top insurance providers in North Carolina and see how they stack up. Knowing their reputation and customer service quality will help you make an informed decision.
Top Insurance Providers in North Carolina
North Carolina is home to numerous insurance companies, but only a few stand out. These companies are known for their exceptional service and competitive rates.
- State Farm
- Nationwide
- GEICO
- Allstate
- Progressive
Each of these providers has a unique set of offerings. While some excel in customer service, others might offer pricing advantages or special features.
Reputation and Customer Service
Choosing an insurance provider isn’t just about numbers. You need to consider their reputation and customer service.
For example, State Farm is often praised for its personalized service and responsive agents. On the other hand, GEICO attracts customers with its user-friendly online platform and competitive pricing.
Pro Tip: Always check customer reviews and ratings before making your decision—they’re the best indicators of a company’s real-world performance!
Comparing Insurance Providers
A side-by-side comparison can make your choice much easier. Here’s how some of the top providers compare:
| Provider | Rating | Pricing | Special Features |
|---|---|---|---|
| State Farm | 4.5/5 | $$ | Personalized Service, Local Agents |
| Nationwide | 4/5 | $$$ | Vanishing Deductible, Accident Forgiveness |
| GEICO | 4.2/5 | $ | User-Friendly App, Discounts |
| Allstate | 4/5 | $$$ | Drivewise App, Claim Satisfaction Guarantee |
| Progressive | 4.1/5 | $$ | Snapshot Program, Bundling Discounts |
Evaluating Financial Stability
Here’s the deal: an insurance provider’s financial stability is crucial. You want to be sure that they can pay out claims when needed.
Check their ratings with agencies like A.M. Best or Moody’s. These ratings indicate a company’s fiscal health and its ability to fulfill policyholder obligations.
Remember, a company with a strong financial backing is more likely to provide reliable service over the long term.
Strategies to Lower Insurance Premiums in NC
Are you tired of watching your insurance premiums eat away at your budget? You’re not alone. In North Carolina, there are proven strategies to help you keep more cash in your pocket.
Here’s the deal: Insurance companies offer plenty of ways to save, but most people aren’t taking full advantage of them. By making some strategic moves, you can significantly reduce your insurance costs without sacrificing coverage.
Practical Ways to Reduce Insurance Premiums
Step #1: Bundle your policies. By combining your home and auto insurance with the same provider, you can often snag a discount of up to 25%. Insurance companies love loyal customers, and bundling is a surefire way to show your commitment.
Step #2: Raise your deductible. This might sound counterintuitive, but increasing your deductible can dramatically lower your monthly premiums. If you’re willing to pay a little more out of pocket in the event of a claim, the savings could be worth it.
Pro Tip: Consider a deductible that aligns with your emergency savings. This way, you benefit from lower premiums without risking financial strain.
Discounts Available for Policyholders
Before you renew your policy, be sure to explore these common discounts:
- Safe driver discount
- Multi-policy discount
- Good student discount
- Low mileage discount
- Anti-theft device discount
Example Scenario of Premium Reduction
Let’s say you currently pay $1,200 a year for auto insurance. After bundling with your homeowner’s policy (saving 15%) and raising your deductible (saving another 10%), your new annual premium could drop to $930.
By implementing these strategies, you not only save $270 a year but also gain peace of mind knowing you’re not overpaying for coverage.
The Role of NC Insurance Regulations
Ever wondered why your insurance premium is higher in North Carolina? It’s not just about the hurricanes or your driving record. State regulations play a massive role in shaping the insurance landscape here.
North Carolina’s insurance regulations are designed to protect consumers while ensuring a fair marketplace for insurers. This balance leads to specific laws that directly influence the types of policies you can get and how much you’re going to pay. Let’s dive into the details.
State-Specific Insurance Regulations
North Carolina mandates insurance companies to follow particular rules that can affect everything from premiums to coverage options. For example, the state regulates the rate at which insurers can increase premiums, which can help prevent sudden, unexpected hikes. BUT, this doesn’t mean rates won’t change. External factors like economic shifts can still cause fluctuations. Here is the deal: Knowing these regulations can arm you with knowledge to make better policy decisions.
Mandatory Insurance Requirements in NC
Before you choose a policy, you need to know what’s required by law. North Carolina mandates specific types of insurance coverage that every driver must have:
- Liability Coverage: Minimum of $30,000 for bodily injury per person and $60,000 per accident.
- Property Damage: Minimum of $25,000 per accident.
- Uninsured Motorist Coverage: Required to protect against uninsured drivers.
Failing to meet these requirements isn’t just risky—it’s illegal.
Impact of Recent Legislative Changes
Recent legislative changes can dramatically alter insurance rates. For example, a new law might adjust the minimum coverage requirements or impose additional fees or taxes on insurers. These changes can lead to an increase or decrease in your insurance premiums. Pro Tip: Always stay updated on legislative developments. They can significantly impact what you pay for insurance.
Customer Reviews and Experiences
Ever wondered how your neighbors feel about their insurance providers? It’s no secret: customer experiences can make or break your decision to choose a particular insurer. In fact, a staggering 93% of consumers read reviews before making a purchase.
But here’s the deal: sifting through hundreds of reviews can be overwhelming. So, let’s break it down. You’ll find that customer reviews in North Carolina often highlight important themes that can guide your policy decisions.
Common Feedback Themes from NC Customers
Before diving into specific experiences, it’s crucial to understand the recurring themes that customers in North Carolina mention about their insurers. These themes can give you a snapshot of what to expect.
- Claims Process: Quick and efficient or slow and cumbersome? This theme pops up frequently.
- Customer Service: Friendly and helpful staff or long wait times? Customer service makes a big impact.
- Price vs. Value: Are policyholders satisfied with the value for money they get?
- Policy Transparency: Clear terms or hidden surprises? Transparency is a common concern.
- Coverage Options: Does the insurer offer a range of options that meet different needs?
How Customer Reviews Can Guide Your Policy Decisions
You’ve probably asked yourself: “How do these reviews actually help?” Well, they can be your best ally when navigating the insurance maze.
Seeing consistent praise for a quick claims process can point you towards a hassle-free experience. On the flip side, repeated complaints about hidden fees should raise a red flag.
Pro Tip:
Always look for patterns in reviews rather than isolated incidents. One negative review doesn’t tell the whole story, but a dozen on the same issue might.
Case Study: A Satisfied Customer’s Journey with XYZ Insurance
Let’s talk about Jane, a homeowner from Charlotte, who had a stellar experience with XYZ Insurance. She filed a claim after a major storm left her roof damaged.
To her surprise, the claims process was seamless. She shared that the representative was not only empathetic but also expedited the process, getting her the funds within a week.
Jane’s story highlights the importance of a responsive claims department. Her positive experience wasn’t just luck; it was the result of consistent service that many others echoed in their reviews.
Summary
As you venture into the world of insurance in North Carolina, remember that knowledge is your greatest asset. By understanding your options and the factors influencing rates, you’re well on your way to making smart choices. Whether you’re looking to switch providers or adjust your current policy, these insights will help you navigate the process with ease and confidence. Here’s to securing the best insurance rates in NC!
FAQ
What types of insurance are available in North Carolina?
In North Carolina, you can find various types of insurance including auto, health, home, life, and renters insurance, each tailored to specific needs and preferences.
How does my location affect my insurance rates in NC?
Your location can significantly impact your insurance rates. Urban areas may have higher rates due to increased risk factors like traffic and crime compared to rural areas.
Can my credit score influence my insurance premiums?
Yes, in North Carolina, a higher credit score may result in lower insurance premiums as it is often viewed as an indicator of financial responsibility.
What are some strategies to lower my insurance premiums in NC?
Consider bundling policies, raising deductibles, and taking advantage of available discounts such as good driver or multi-policy discounts to lower your premiums.
Are there mandatory insurance requirements in North Carolina?
Yes, North Carolina requires minimum liability coverage for auto insurance, and other types of insurance may have specific mandates depending on your circumstances.
